

Macro
Last week’s retrospective:

Indeed, the ride was too far from being smooth and Michigan Consumer Sentiment was a piece that brought a new portion of volatility in the markets on Friday.
Year-ahead inflation expectations in the United States climbed to 4.3% in February 2025, the steepest since November 2023. The major indices reacted by falling ~1%.

Sticky inflation is a major risk in the current president's administration. Eyes on CPI data next week.
There are a few more things on macro.
The yield curve inversion is unwinding — the spread between 10Y and 2Y US Treasuries has turned positive again. Historically, this shift has often preceded recessions and market downturns, though with a lag.

Does this mean an imminent bear market? Not necessarily, but it's always a good idea to consider potential risks.
I see 3 of the most probable macro scenarios for the market today:
Soft Landing: inflation decreases, the labor market cools, economic growth is robust => growth and small-to-mid caps outperform the broad market over the next 5-year bull market.
Risk of Recession Materializes => a bear market regime kicks in => rates cut => recovery period after.
Sticky Inflation => no rates cut => economy stays resilient => markets rise until either the Soft Landing or Recession scenarios play out further.
Keep in mind the market lives in the context of Soft Landing today.
Earnings Insights
I often get asked by retail investors where to find trading or investing ideas in the stock market. There is a “chart narrative problem” deeply rooted in the retail market — many traders start and end their analysis with charts.
Imagine if a doctor prescribed treatment based solely on result metrics like heart rate, blood pressure, and body temperature. Trading charts work the same way — they reflect outcomes, not root causes.
The best way to start your investing journey isn’t by analyzing fundamentals right away but by diving into quarterly earnings call transcripts. Here, company management serves as your guide to their industry and business. Reading these transcripts will not only broaden your overall market perspective but also help you develop a personal framework for understanding business models and decision-making based on qualitative factors.

Start with the quarter reports and make it a habit, and you will quickly see how your stock-picking process levels up.
There is a way to optimize this process. I use this Earnings Call Summarizer at work, which saves me hours of reading the call transcripts. Reach out if you want to try it.
I’ve been reading earnings reports lately, enjoy a breakdown of the most valuable quotes from management:
"We did set an all-time record for upgraders, so we've never seen a higher level of upgraders before." - Tim Cook, CEO
"The macro-environment continues to be very, very strong and solid, the labor environment strong, 4.1% unemployment. I think the fundamentals are good and so I think that the hiring and companies still being profitable and there seems to be an awful lot of optimism in the US market in particular." - Don McGuire, CFO
Shane Trigg, President and CEO
"We believe the high interest rate environment will continue to limit our current customers' ability to expand their portfolios."
"The generative AI-powered capabilities of Realm-X, automate routine tasks and key workflows, streamline communications and enable property managers to transform their operational performance."
Below, I cover two promising stock ideas that I personally hold in my portfolio. These stocks benefit from the MAGA (“Make America Great Again”) strategy as a major tailwind and have the potential for significant revaluation. They will be the first additions to the model portfolio this year.
Need more info about the project — read About.
Jim Umpleby, Chairman and CEO:
"Construction spend in North America remains healthy, primarily driven by large multi-year projects and government-related infrastructure investments supported by funding from the IIJA."
"In Asia Pacific outside of China, we expect soft economic conditions to continue into 2025."
"We anticipate weak economic conditions in Europe will continue and a healthy level of construction activity in Africa and the Middle East."
"We continue to believe the energy transition will support increased commodity demand over time, expanding our total addressable market and providing further opportunities for long term profitable growth."
"We are leveraging over 1.5 million connected reporting assets and digital tools."
"We remain proud of our dividend aristocrat status as we have paid higher annual dividends for 31 consecutive years." - Andrew Bonfield, Chief Financial Officer
"We believe the President wants to use policy and regulations in ways that will strengthen, not harm domestic manufacturers like GM." - Mary Barra, CEO
"We are optimistic in our robust product portfolio and our ability to drive market share expansion through strong ICE sales, complemented by a strategically diverse lineup of EVs." - Paul Jacobson, CFO
"We expect to see a run rate savings of about $1 billion on an annualized basis by ending robotaxi development." - Mary Barra, CEO
"We continue to gain momentum with our GenAI book of business growing to over $5 billion inception-to-date, up by about $2 billion quarter-over-quarter." - Arvind Krishna, Chairman, President and CEO
"Clients are reprioritizing their IT spending towards digital transformation and AI initiatives for cost optimization and operational efficiency." - James Kavanaugh, Senior Vice President and CFO
Satya Nadella, CEO: "As AI becomes more efficient and accessible, we will see exponentially more demand."
"Enterprises are beginning to move from proof-of-concepts to enterprise-wide deployments to unlock the full ROI of AI."
"We are still on track to launch a more affordable model in the first half of 2025 and will continue to expand our lineup from there." - Vaibhav Taneja, CFO
Elon Must, CEO:
"I see a path for Tesla being the most valuable company in the world by far, not even close."
"We expect to use several thousand humanoid robots at Tesla for the most boring, annoying tasks in the factory."
"We have our second factory, which is in Shanghai, that's starting operation and we're building a third factory."
Palantir Case
This earnings season lots of prominent big tech players like MSFT 0.00%↑, AMZN 0.00%↑ didn’t meet analysts’ expectations on AI future guidance and got devalued.
But not Palantir PLTR 0.00%↑. AI isn’t just a future bet for Palantir — it’s happening right now. With rapid scaling, efficiency-driven AI deployment, and massive enterprise adoption, Palantir is positioned to dominate. But current valuation is my concern, but who cares.
More on this in my thread on X.
Model Portfolio Additions
I got these 2 stocks having MAGA (“Make America Great Again) strategy as a major tailwind and could potentially reevaluate drastically. They will be the first additions to the portfolio this year. If there will be any interim decisions I will communicate on Chat. Stay tuned.
MP Materials Corp.
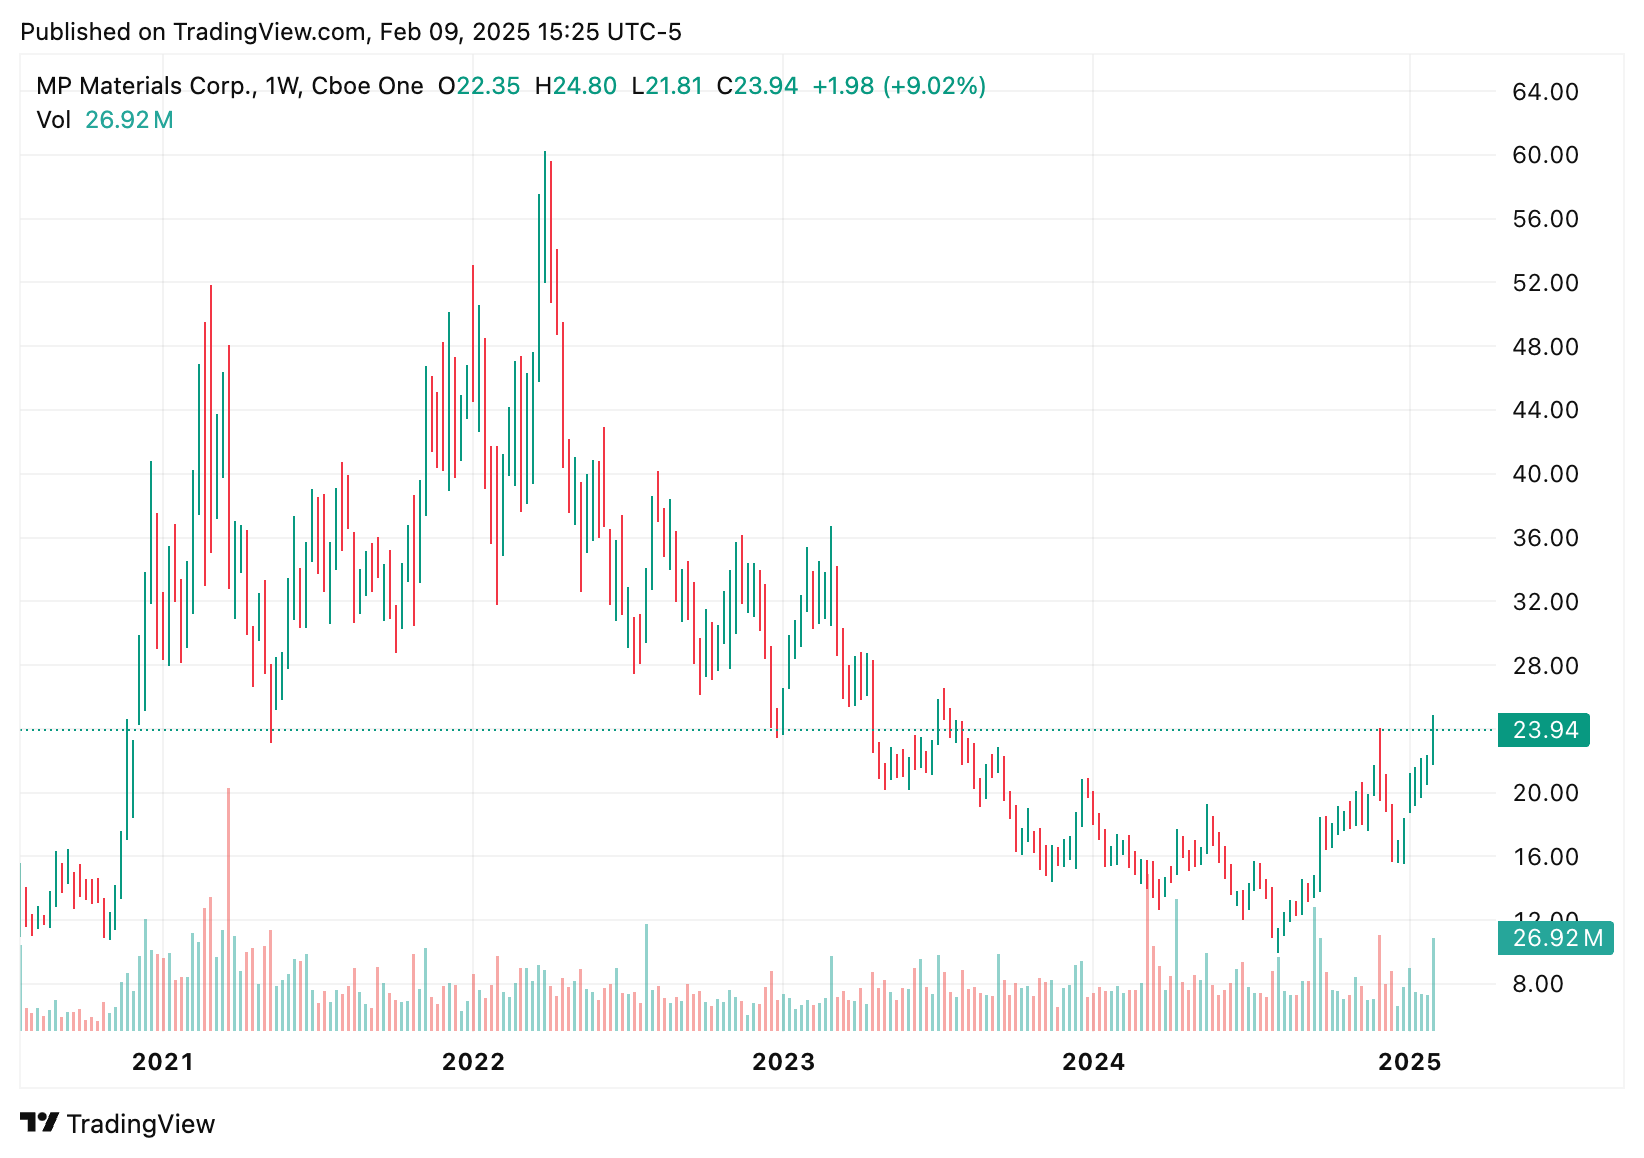
Current Price: $23.94
Sector: Basic Materials
Industry: Industrial Materials
Mcap: ~$4 bln
Short Interest: 12%
Monthly Historic Volatility: 21%
Operations: MP Materials Corp. is the largest producer of rare earth materials, operating the Mountain Pass Rare Earth Mine, the only large-scale site in North America, and primarily supplying the critical neodymium-praseodymium segment for electric vehicle magnets. Holding a significant market share (~20%), the company is positioned against fierce competition, primarily from Chinese players benefiting from lower production costs.
Factors of potential stock price appreciation:
The anticipated impact of the 45X Advanced Manufacturing Production Tax Credit stimulating onshore manufacturing in the US.
Better-than-expected Earnings on the 20th of February 2025.
The company has an exclusive long-term supply agreement with General Motors, and the latter doing very well in the EV industry set to expand its production in the US.
Valuation: the company generated a loss in FY2024 with the potential to reach profitability from the next year. In place an aggressive growth company profile — sales are about to increase by ~70% annually over the next 2 years, EPS from -$0.4 this year to ~$1 in 2026.
The growth profile and onshoring trend under the new presidency administration make this company a decent candidate for a turnaround.
It trades at 20x P/S multiple and there is no reason for this to get lower. By implying this multiple to the FY2025 sales we derive a price target of ~$40 per share => ~70% upside from the current price.
Balance Sheet: there are $900 mln of cash and equivalents on the company's balance, PPE valued at $1.2 bln which makes the long-term borrowing of $940 manageable.
Risks: the one major foreseen risk is if the company won’t be able for any reason to ramp up its new facilities in the US and bit the competition with the importers of Chinese goods.
Price Chart:
Mind Medicine
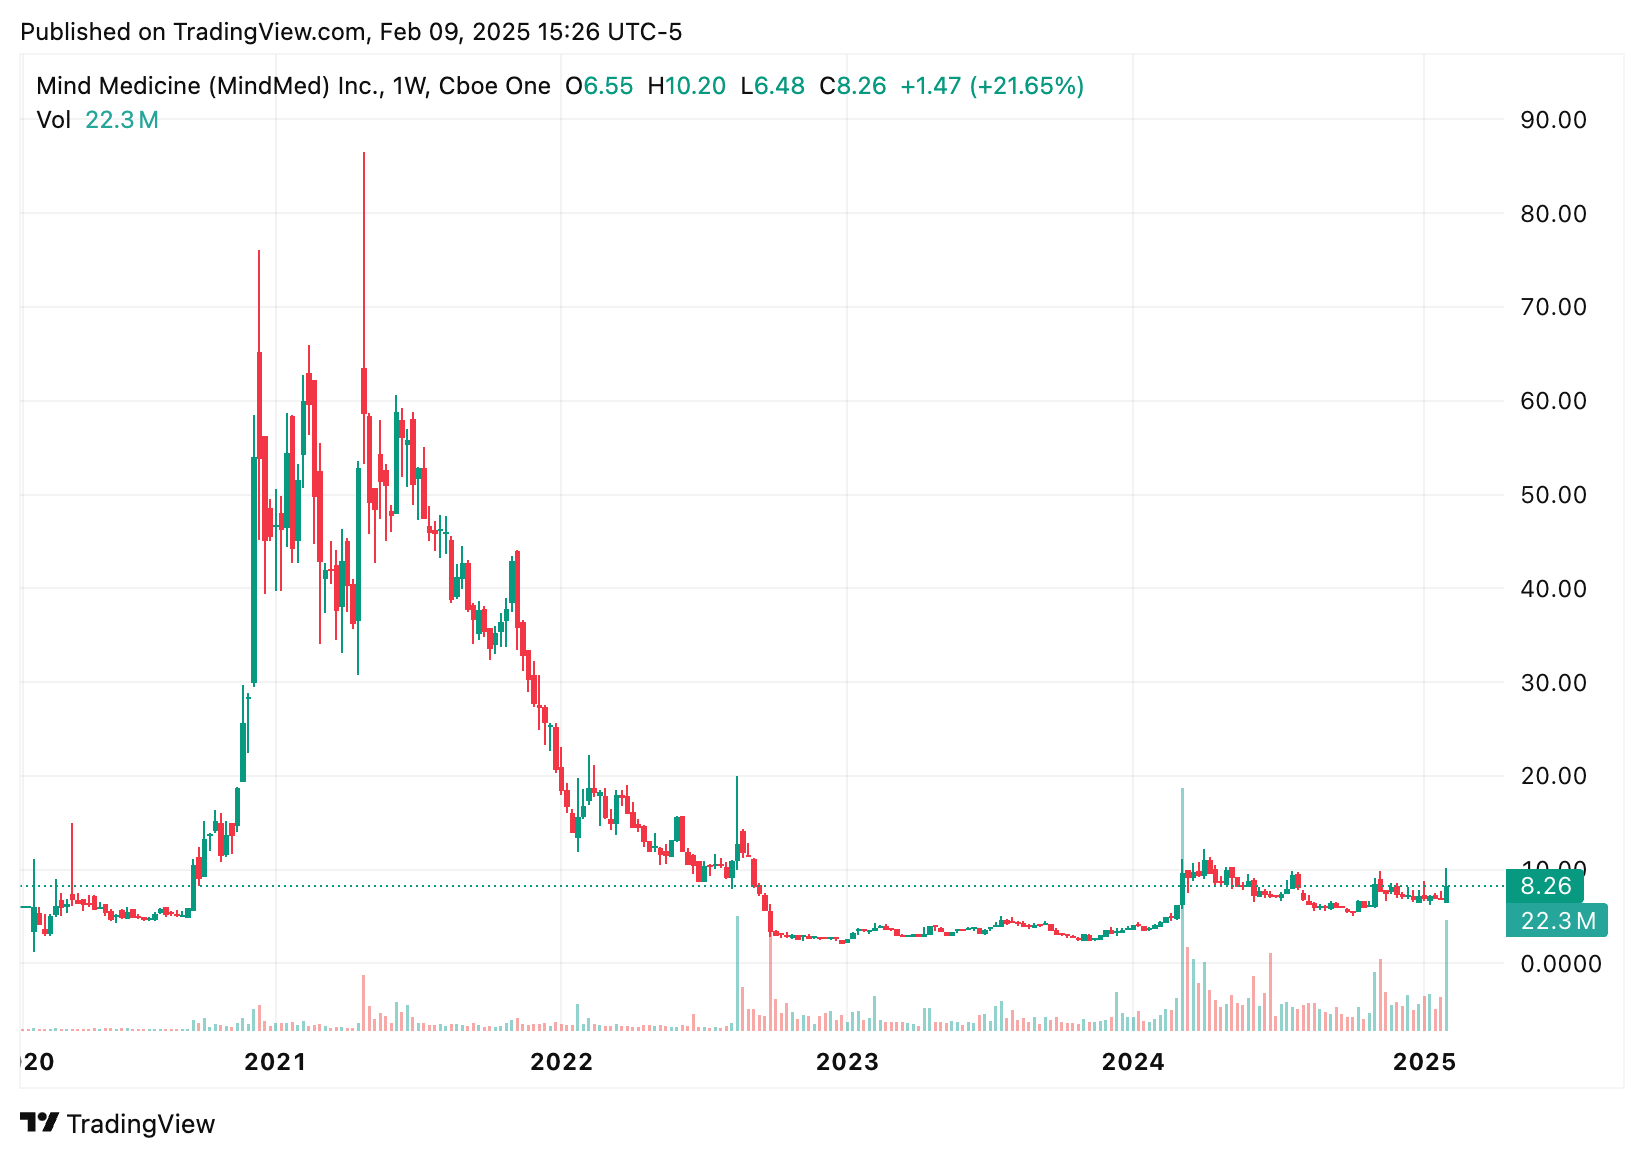
Current Price: $8.26
Sector: Healthcare
Industry: Biotechnology
Mcap: ~$658 mln
Short Interest: 13%
Monthly Historic Volatility: >100%
Operations: Mind Medicine is a clinical-stage biopharmaceutical company developing novel product candidates to treat brain health disorders, such as generalized anxiety disorder (“GAD”), attention deficit hyperactivity disorder (“ADHD”), autism spectrum disorder (“ASD”), or major depressive disorder (“MDD”). They are producing pharmaceutically optimized product candidates derived from psychedelic and empathogen drugs. They try to produce safe pharmaceutical drugs based on drugs like MDMA (Ecstasy), LSD or Mushrooms by reducing unwanted effects.
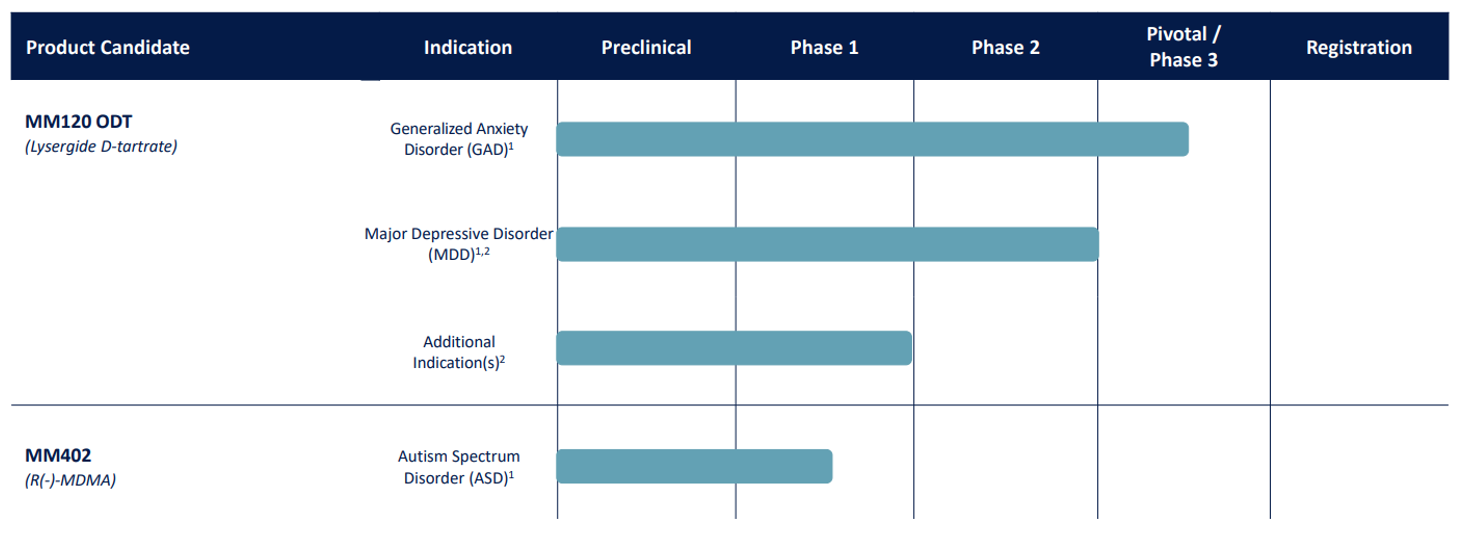
Their lead product candidates are:
MM120 = optimized form of LSD intended for generalized anxiety disorder (“GAD”)
MM402 = optimized form of MDMA for autism spectrum disorder (“ASD”) or “PTSD”
Factors of potential stock price appreciation:
Robert F Kennedy Jr.'s (RFK) nomination as HHS secretary. “He's going to help Make America Healthy Again. He wants to do some things and we're going to let him go do it.”
Mind Medicine will benefit greatly from any regulatory reliefs and/or increased funding/research budgets:
RFK distrusts the pharmaceuticals and criticizes the FDA for its “aggressive suppression of psychedelics”.
RFK said half the research budgets from the NIH should be directed toward preventive, alternative, and holistic approaches to health.
RFK has highlighted the use of psychedelics, like MDMA, for treating conditions such as PTSD in veterans.
Earnings Announcement on 28th of February 2025.
News about the ongoing MM402 Phase I trial (part 1) before March 2025.
News about the end of the MM120 Phase III trial before March 2025.
Valuation: you can’t rate this company based on P/E or Sales multiple as there are no earnings or sales yet. They expect their first revenue in 2026.
Although I don’t have a price target, this stock can easily double in the next six months, based on positive trial/product news or regulatory relief.
Balance Sheet: the company has enough cash to operate until 2027, and if trials go smoothly, raising more funds will not be a problem.
Risks: RFK is not yet confirmed as HHS secretary. If he is not confirmed, the trade loses its biggest catalyst. This is a tail risk trade — low probability of play out and massive return if happens. For this kind of trade, I usually allocate no more than 5% of portfolio size.
Price Chart:
Reach out if you have any questions.
More details on the investment mandate I follow in this letter in the next publications.
Disclaimer
I’m not affiliated with a broker, a dealer, or a registered investment adviser, and this letter represents my thoughts only. The presented information is a part of research I conduct in my work and there is always a place for a mistake or unrealized expectations. Please, do your own research.
I have the mentioned companies MP Materials Corp. (MP) and Mind Medicine (MNMD) in my own portfolio, thought my trading strategy and horizon could be different.
The information in this report is not intended to be, nor does it constitute, investment advice or recommendations.